HDB vs Condo: Cost, Space and Daily Life Compared, with Hougang Numbers
What you actually pay per square foot, what you get for it, how the loan rules differ, and how daily life changes when a Hougang family moves from an HDB flat to a condo.
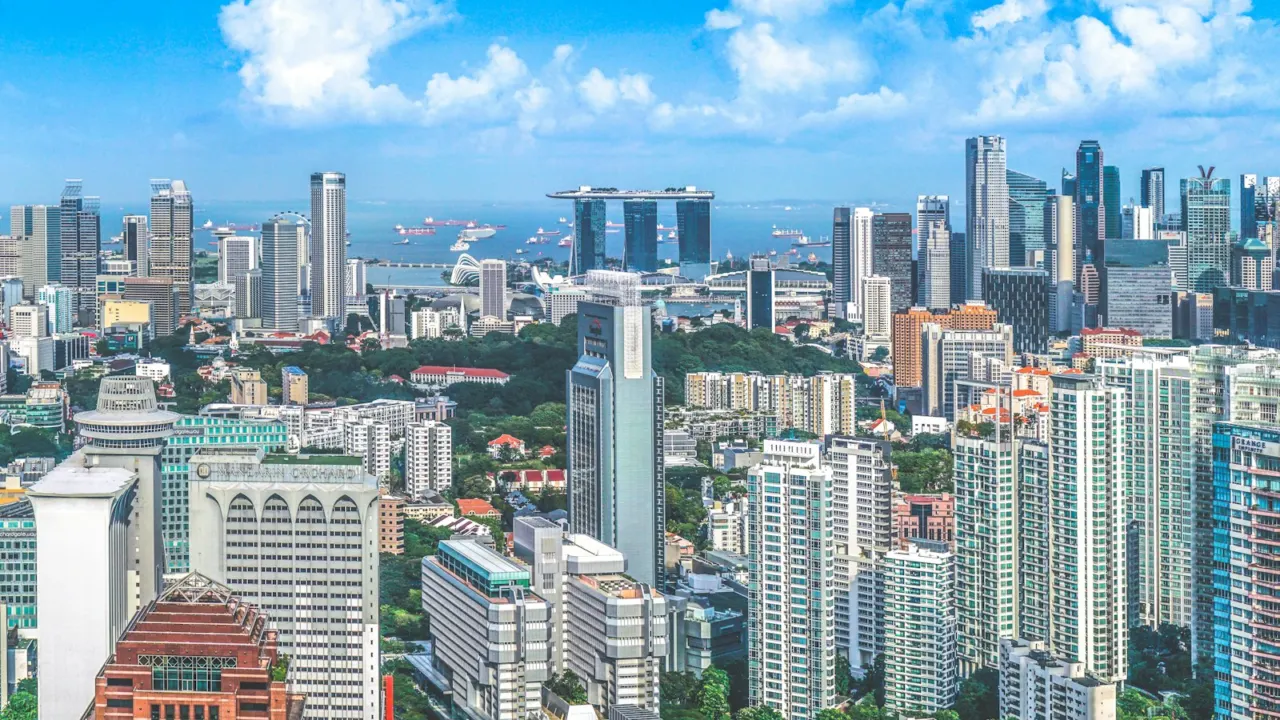
“HDB or condo?” sounds like a simple question, but it bundles several: how much you pay for each square foot, how much space you actually get, how the loan rules differ, and what everyday life feels like. This guide takes each in turn using Hougang figures, and uses LinkTown Residences (Hougang Central Residences) as the new-launch example. Its prices have not been released, so the condo numbers below are analysts’ estimates.
At a glance
| HDB flat (resale, Hougang) | Private condo | |
|---|---|---|
| Typical price per sq ft | About S$600–620 psf (2026 median, 4-room and 5-room) | About S$1,700–1,900 psf for Hougang resale condos; S$2,500–2,600 psf expected for LinkTown (estimate) |
| Who can buy | Eligible Singapore Citizens and PRs under HDB rules | Anyone; ABSD depends on residency and property count |
| Loan | HDB loan or bank loan | Bank loan only |
| Servicing limits | MSR 30% and TDSR 55% | TDSR 55% only |
| Minimum occupation | 5 or 10 years depending on flat type | None |
| Facilities | Town amenities, void decks, parks | Pool, gym and shared facilities; at LinkTown, a mall and bus interchange on the same site |
| Monthly running costs | Service and conservancy charges | Maintenance fees set by the MCST, usually higher |
Price: the per-square-foot gap
We calculated Hougang medians from HDB’s resale transactions on data.gov.sg for January to September 2026:
| Flat type | Transactions | Median price | Median size (Hougang) | Rough psf |
|---|---|---|---|---|
| 3-room | 198 | S$450,000 | 67 sqm (721 sq ft) | ~S$625 |
| 4-room | 459 | S$618,888 | 93 sqm (1,001 sq ft) | ~S$620 |
| 5-room | 193 | S$775,000 | 120 sqm (1,292 sq ft) | ~S$600 |
| Executive | 100 | S$960,000 | 147 sqm (1,582 sq ft) | ~S$605 |
Psf is our rough division of the two medians, not a published figure. Prices vary widely with remaining lease, floor and distance to the MRT.
On the condo side, based on reported transaction data, Riverfront Residences averaged about S$1,736 psf and The Florence Residences about S$1,877 psf over the 12 months to mid-2026. Analysts expect LinkTown Residences to average around S$2,500–2,600 psf. So the same floor area costs roughly three times as much in a Hougang resale condo, and about four times as much in a new integrated launch. What that premium buys is the rest of this guide.
Space: similar on paper, different in feel
A 4-room flat and a 3-bedroom condo both have three bedrooms, and their floor areas overlap. HDB’s typical 4-room is about 86–94 sqm (925–1,010 sq ft); the indicative LinkTown 3-bedroom is 1,066 sq ft, based on the developers’ Parktown Residence and not LinkTown’s final plans. The difference is in what the area includes. Condo strata area can count the balcony, AC ledge, household shelter and planter areas, so internal living space is often smaller than the headline suggests. HDB 5-room and Executive flats, at 110–154 sqm, are hard to match in a new condo without moving to the 4 or 5-bedroom types.
Our guide to reading a condo floor plan shows what to check, and the indicative layouts are on the floor plans page.
Running costs
- Maintenance fees: condo owners pay the MCST a monthly fee, split between a management fund and a sinking fund and charged by share value. It is usually well above HDB service and conservancy charges. LinkTown’s fees are not announced; see how condo maintenance fees work.
- Property tax: both are taxed on Annual Value at owner-occupier rates if you live there, but a condo’s higher Annual Value usually means a larger bill. Check with IRAS.
- Stamp duty and fees: Buyer’s Stamp Duty rises with price, so a S$2.7m condo attracts about S$104,600, against about S$13,200 on a S$620,000 flat. Verify with IRAS.
Our cost of owning a condo guide adds the rest up.
Financing: MSR vs TDSR
An HDB flat bought with a loan is tested against the Mortgage Servicing Ratio: property loan instalments may not exceed 30% of gross monthly income, alongside the 55% TDSR. A private condo needs a bank loan and is tested only against TDSR, using a 4% stress rate. In practice this means a household can often borrow more for a condo than for a flat on the same income, but the condo also costs far more. Our HDB loan vs bank loan guide covers rates and flexibility. Try a condo instalment here:
Maximum loan & affordability (TDSR)
Estimates for illustration only, based on published IRAS/MAS rules. Rates change; confirm with IRAS, your bank and your lawyer.
Daily life
What a condo adds
- A pool, gym and function rooms within the development, plus security and managed common areas.
- No MOP, so you can sell or rent out the whole unit when plans change (private homes have a minimum rental period of three consecutive months).
- A wider pool of future buyers, including PRs and foreigners.
- At Hougang Central Residences specifically, a direct link to Hougang MRT (NE14), a future Cross Island Line interchange around 2030, and a new mall and bus interchange on the same site.
What HDB keeps
- Much lower monthly commitments, leaving room for savings, travel or children’s costs.
- Larger flats for the money, especially 5-room and Executive.
- Established neighbourhoods with hawker centres, markets and schools a short walk away. Condo residents in Hougang use the same amenities, of course.
Who each suits
Staying in HDB often makes sense if your household wants low fixed costs, has limited cash for a 25% down payment, or needs the space of a 5-room or Executive flat. A condo suits households that value facilities and location, want freedom to sell or rent without an MOP, and can carry the loan comfortably under TDSR with a buffer. Many families do both, in order: a flat first, then a condo after the MOP. If you are still at the flat stage, our Hougang BTO vs condo guide looks at the BTO side. Our HDB upgrader guide works through that move with numbers.
Prices, rules and fees change. Verify with HDB, IRAS, MAS and your bank before deciding. When LinkTown’s prices are released they will appear on the price list page.
Register to get LinkTown Residences prices and floor plans as soon as they’re released.
Frequently asked questions
Is a condo much more expensive than an HDB flat in Hougang?
Yes. Hougang HDB resale flats changed hands at roughly S$600–620 psf (median) in the first nine months of 2026, based on HDB resale data. Nearby resale condos have averaged around S$1,700–1,900 psf, and analysts expect LinkTown Residences at around S$2,500–2,600 psf.
Is a condo bigger than an HDB flat?
Not always. A 4-room HDB flat is typically about 86–94 sqm (roughly 925–1,010 sq ft), which is similar to many new 3-bedroom condo units. Condo strata area can also include the balcony, AC ledge and household shelter.
Can I use an HDB loan for a condo?
No. HDB loans are for HDB flats only. A condo needs a bank loan, which is tested against the 55% Total Debt Servicing Ratio. HDB flats bought with a loan are also subject to the 30% Mortgage Servicing Ratio.
Who should stay in HDB rather than buy a condo?
Households that want low monthly commitments, have limited cash for a 25% down payment, or value a large flat over facilities often do better staying in HDB. A condo suits buyers who want facilities, a specific location and a wider pool of future buyers, and can carry the higher cost.
More buying & finance guides
All guides
Buying & finance
PR Stamp Duty Singapore: Buying a Condo as a Permanent Resident
PR stamp duty on a condo, CPF use, the HDB sell-within-six-months rule and mixed SC-PR couples, with illustrative LinkTown figures.
Buying & finance
ABSD Remission for Married Couples: Conditions, Deadlines and New-Launch Timing
ABSD remission for married couples: who qualifies, the six-month sale rule, how the clock runs from TOP on a new launch, and how to claim.
Buying & finance
PSF Meaning in Singapore Property: Price per Square Foot, PSM and Quantum Explained
Price per square foot, psm, strata area and quantum explained, with worked examples using LinkTown’s indicative unit sizes.